Business
Funding the Future: Shs. 593,646 Billion Investment in National Development Plan (NDP IV) with 70% Government Support – Ministry of Finance

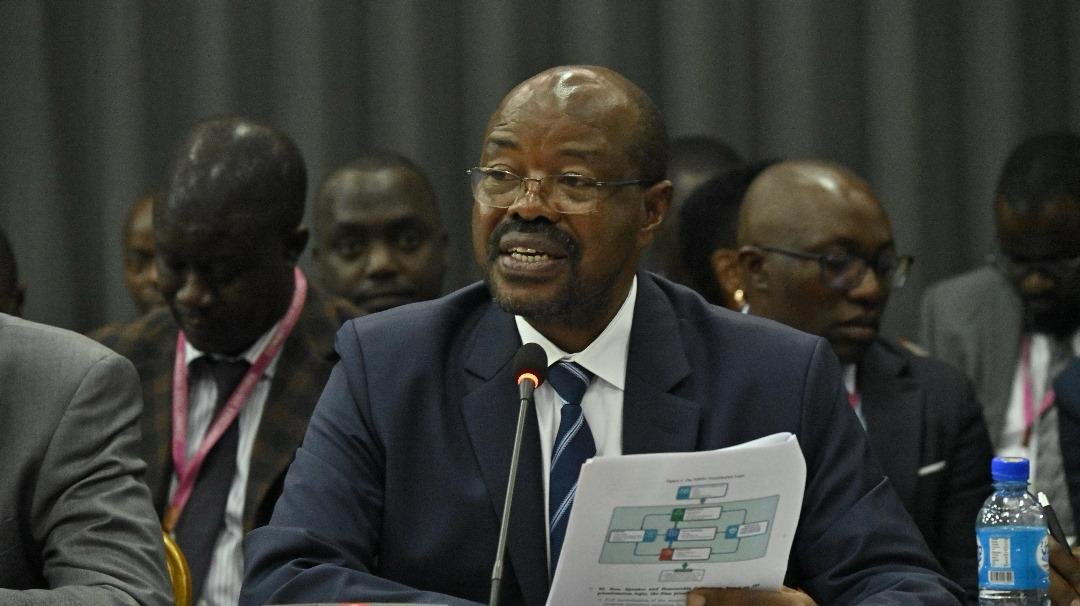
On January 7, 2025, key government officials presented to the Parliamentary Committee on Budget. Attendees included Hon. Amos Lugoloobi (State Minister of Finance for Planning), Hon. Henry Musasizi (Minister of State for General Duties), and other experts from the Ministry of Finance and the National Planning Authority. Their objective was to explain the Fourth National Development Plan (NDPIV).
What is the National Development Plan?
The National Development Plan serves as a comprehensive blueprint for the country, helping Uganda determine its priorities to improve the quality of life for all citizens. The government has previously implemented three plans (NDPI, NDPII, and NDPIII), and they are now focused on the fourth one, known as NDPIV, which will span the years 2025/26 to 2029/30.
Why is this important?
NDPIV is informed by lessons learned from the previous plan (NDPIII) and aims to achieve ambitious targets, such as Uganda Vision 2040, which envisions the ideal state of Uganda by the year 2040. Additionally, the government aspires to grow the economy tenfold over the next 15 years. To develop this plan, extensive consultations were held with experts, local governments, and international stakeholders.
What is the goal of NDPIV?
The primary objective of NDPIV is to enhance income levels, create jobs, and strengthen the economy. The plan features a central theme: “Sustainable Industrialization for Inclusive Growth, Employment, and Wealth Creation.” This emphasizes leveraging industries, including agriculture, manufacturing, and technology, to generate employment and promote collective advancement.
What are the key components of the plan?
NDPIV focuses on five major goals:
- Increase production and value addition: Enhance agriculture, manufacturing, mining, tourism, and technology to produce better quality products.
- Improve education and health: Equip individuals with new skills and ensure access to healthcare so they can perform better in their jobs.
- Support the private sector: Foster the growth of private businesses to boost job creation.
- Develop infrastructure: Invest in better roads, housing, and energy systems to facilitate business operations and improve living standards.
- Enhance government efficiency: Strengthen the government’s functionality to support national growth.
What will happen if the plan succeeds?
If NDPIV is successfully implemented:
- Uganda’s economy (measured as GDP) could grow significantly, increasing from $53.2 billion in 2023/24 to $158 billion by 2029/30.
- Average monthly incomes may rise from Shs. 202,131 to Shs. 578,635.
- There will be a reduction in poverty levels, with more people gaining access to banks and financial services.
What is the estimated cost?
The total cost of implementing the NDPIV is projected to be Shs. 593,646 billion over five years. Approximately 70% of the funding will come from the government, while the remaining 30% will be sourced from private businesses.
What happens next?
The government has submitted the plan to Parliament for approval. If Parliament endorses it, Uganda will commence work on this extensive plan aimed at improving the lives of its citizens.
In summary, the Fourth National Development Plan (NDPIV) is a strategic initiative designed to promote growth, job creation, and overall betterment for Uganda. It acts as a roadmap for the country’s future!
Business
Standard Chartered Uganda Retail Banking Migration to Absa Set for November 2026
Standard Chartered Uganda’s retail banking migration to Absa is set for November 2026. Here’s what customers need to know about account transfers, digital banking registration, debit cards, recurring payments, and customer support.
Standard Chartered Bank Uganda’s Wealth and Retail Banking (WRB) business is scheduled to migrate to Absa Bank Uganda on November 13, 2026. Customers can access their Absa accounts, services, and digital banking channels starting November 16, 2026.
In separate communications to customers, both banks outlined the transition timelines and arrangements, which will involve transferring customers’ existing banking relationships to Absa.
On October 13, 2026, Standard Chartered confirmed that the migration would be completed on November 13. The bank assured customers that their existing account terms and conditions, banking facilities, and services would remain unchanged until the migration is fully completed.
Absa Bank Uganda has indicated that final migration and integration activities will occur over the weekend of November 13-15, 2026. Access to Absa accounts and banking channels will commence on November 16.
Absa has assured customers that their current banking arrangements will remain unchanged after the transfer. This includes current and savings accounts, term deposits, loans, insurance policies, wealth products, and other banking facilities such as overdrafts.
The bank has confirmed that existing loan terms and repayment arrangements, as well as the terms, conditions, and benefits associated with other banking products, will remain the same.
As part of the transition, customers will receive separate communications containing their new Absa account details. These details may be required when registering for Absa digital banking services.
Customers will need to set up their digital banking profiles using the Absa Uganda mobile application after receiving confirmation that digital access has been enabled.
The registration process involves downloading the official Absa Uganda app, selecting the “Standard Chartered Customer” option, and providing the required identification details, date of birth, and new Absa account number. Customers will then complete facial verification, create a new password, and register their primary device before setting up a four-digit passcode.
Customers’ existing Standard Chartered usernames will remain unchanged; however, they will need their new passwords and passcodes to access their profiles from November 16, 2026, onwards.
Absa has also confirmed that debit cards are currently being processed, and customers will receive further information on delivery arrangements through the bank’s approved service providers. Existing cheque books will be replaced and delivered alongside the new debit cards, with collection available from the Standard Chartered Bank Speke Road Branch as an alternative.
Customers are encouraged to monitor official SMS and email communications from Absa to obtain their new account details. Once received, these details should be shared with employers, service providers, and other organizations that make payments to or collect payments from their accounts.
Customers should also review standing orders, direct debits, subscriptions, and other recurring payment arrangements linked to their accounts, following Absa’s instructions for any necessary updates.
To prepare for digital banking registration, customers should download the official Absa Uganda mobile application when instructed and have their National Identification Number (NIN) or passport number (for non-Ugandan nationals), date of birth, and new Absa account number ready. Registration should only be completed once the bank confirms that digital access is enabled.
Customers are also advised to monitor official communications regarding the delivery or collection of their new debit cards and replacement cheque books. With final integration activities scheduled for November 13-15, customers should plan accordingly and follow official instructions from both banks regarding changes to their accounts and services. Until the migration is complete, they should continue using the existing banking channels of Standard Chartered.
Until the migration is complete, Standard Chartered customers may continue to access banking services through the bank’s existing branches, ATMs, contact centers, and Relationship Managers.
For assistance before the migration, customers can reach Standard Chartered at ug.service@sc.com or through its 24-hour helplines at +256 313 294 100 and +256 200 524 100.
After the transition, customers can contact Absa through the relevant customer support channels. Personal banking customers can email Absa.Uganda@absa.africa, Prestige customers can reach out at PrestigeBanking.Uganda@absa.africa, Premier customers can contact PremierBanking.Uganda@absa.africa, and SME customers can use BusinessBanking.Uganda@absa.africa.
Customers can also call Absa’s toll-free line at 0800 222 333 or use +256 312 218 348 for assistance.
Business
What Uganda’s Maize Story Tells Us About Future Opportunities
Maize is at the heart of Uganda’s farms, feeding families and generating livelihoods. With 69% of agricultural households growing it and 2.8 million metric tonnes produced, the numbers reveal a crop with enormous importance and opportunity.
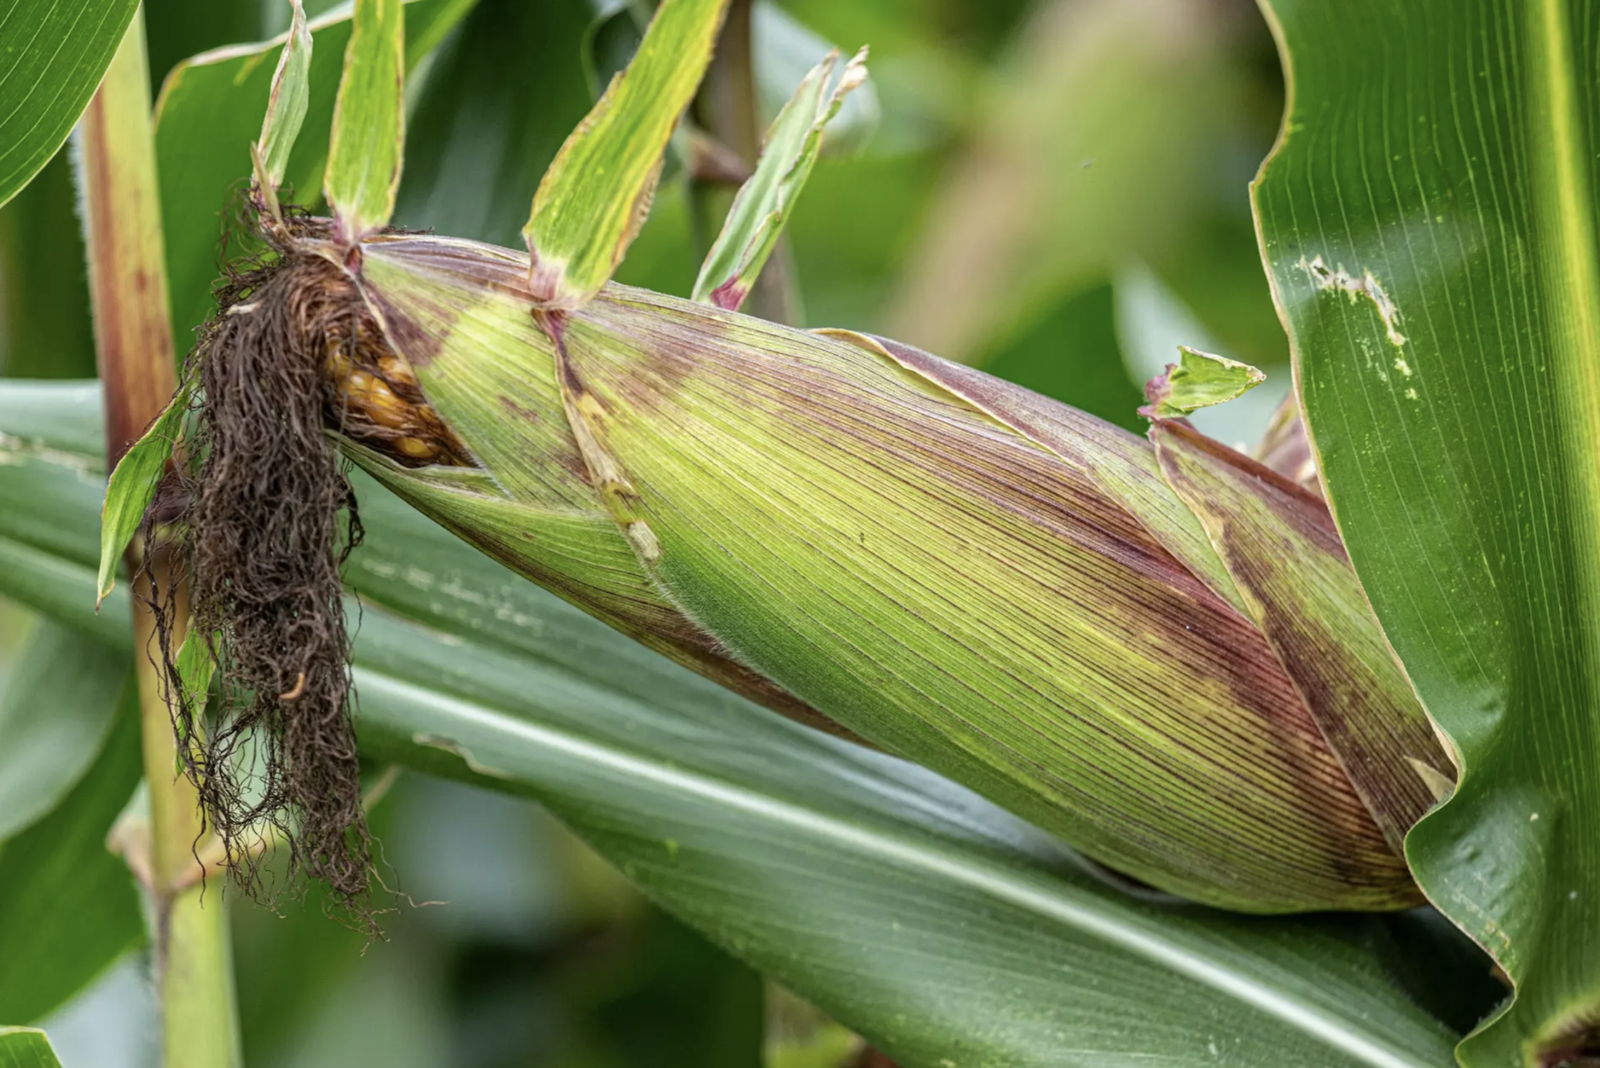
If you ask any Ugandan farmer what they cultivate, there’s a high likelihood they’ll say maize. According to the Uganda Bureau of Statistics (UBOS), maize is the most widely grown crop in the country, cultivated by 69% of all agricultural households. It is more than just a crop; it represents a national habit, a source of livelihood, and a daily meal for millions of families.
In a recent agricultural season reported by UBOS, Ugandan farmers produced 2.8 million metric tonnes of maize. This output is not trivial; it reflects the hard work of hundreds of thousands of smallholder farmers across the country, from the central region to the west, who plant, tend to, and harvest this grain season after season.
The regions that excel in maize production tell an important story. Buganda North leads the country with 710,000 metric tonnes produced in that season, followed by Bunyoro with 561,000 metric tonnes and Buganda South with 266,000 metric tonnes. Together, these regions contribute well over a million tonnes of maize annually, highlighting the concentration of agricultural effort that has made maize the backbone of Uganda’s crop economy.
What happens to Uganda’s maize after it’s harvested is as significant as the quantity produced. UBOS data indicates that over 63% of the maize is sold in its raw, unprocessed form directly from farms to markets. Meanwhile, approximately 27.4% is retained by the households that grow it, providing food for their own families.
This distribution underscores maize’s dual role in Uganda: it serves both as a source of income and a safety net for food security. For many rural households, the same sack of maize sold at the local market this week might have fed the family just last month.
Maize’s rise has not occurred in a vacuum. Over the past decade, UBOS survey data shows a clear trend in Ugandan agriculture: households are shifting away from crops such as millet and beans and increasingly favoring maize, cassava, and bananas. Whether influenced by changing preferences, improved market access for maize, or consistent performance in various seasons, this trend toward maize has been steady.
We are closely studying this national picture. While we have not yet broken ground, we are in the early stages of deliberately planning the foundation for a farm that will be launched in the coming years. The data underscores why maize is central to our plan: it is the crop that Ugandan households already trust, grow, and rely on for both income and food security.
Starting a farm from scratch requires us to understand the market as it currently exists, not as we envision it. This means listening to what the data reveals about how Ugandan farmers grow, sell, and consume maize, which will inform the type of farm we aspire to create.
The seven out of ten farming households that already grow maize in Uganda are more than just a statistic; they are the community we are preparing to join.
Source: Uganda Bureau of Statistics (UBOS), 2019 Agricultural Survey; the most recent UBOS release with this level of crop-specific detail.
Business
Bank of Uganda Sets A Bold Push Toward Digital Payments With New Cash Withdrawal Limits.
The Bank of Uganda has introduced new over-the-counter cash withdrawal limits effective 1 January 2027, capping individuals at UGX 50 million daily and corporates at UGX 250 million. The policy aims to accelerate digital payments while sparking debate on its impact on cash-reliant sectors.
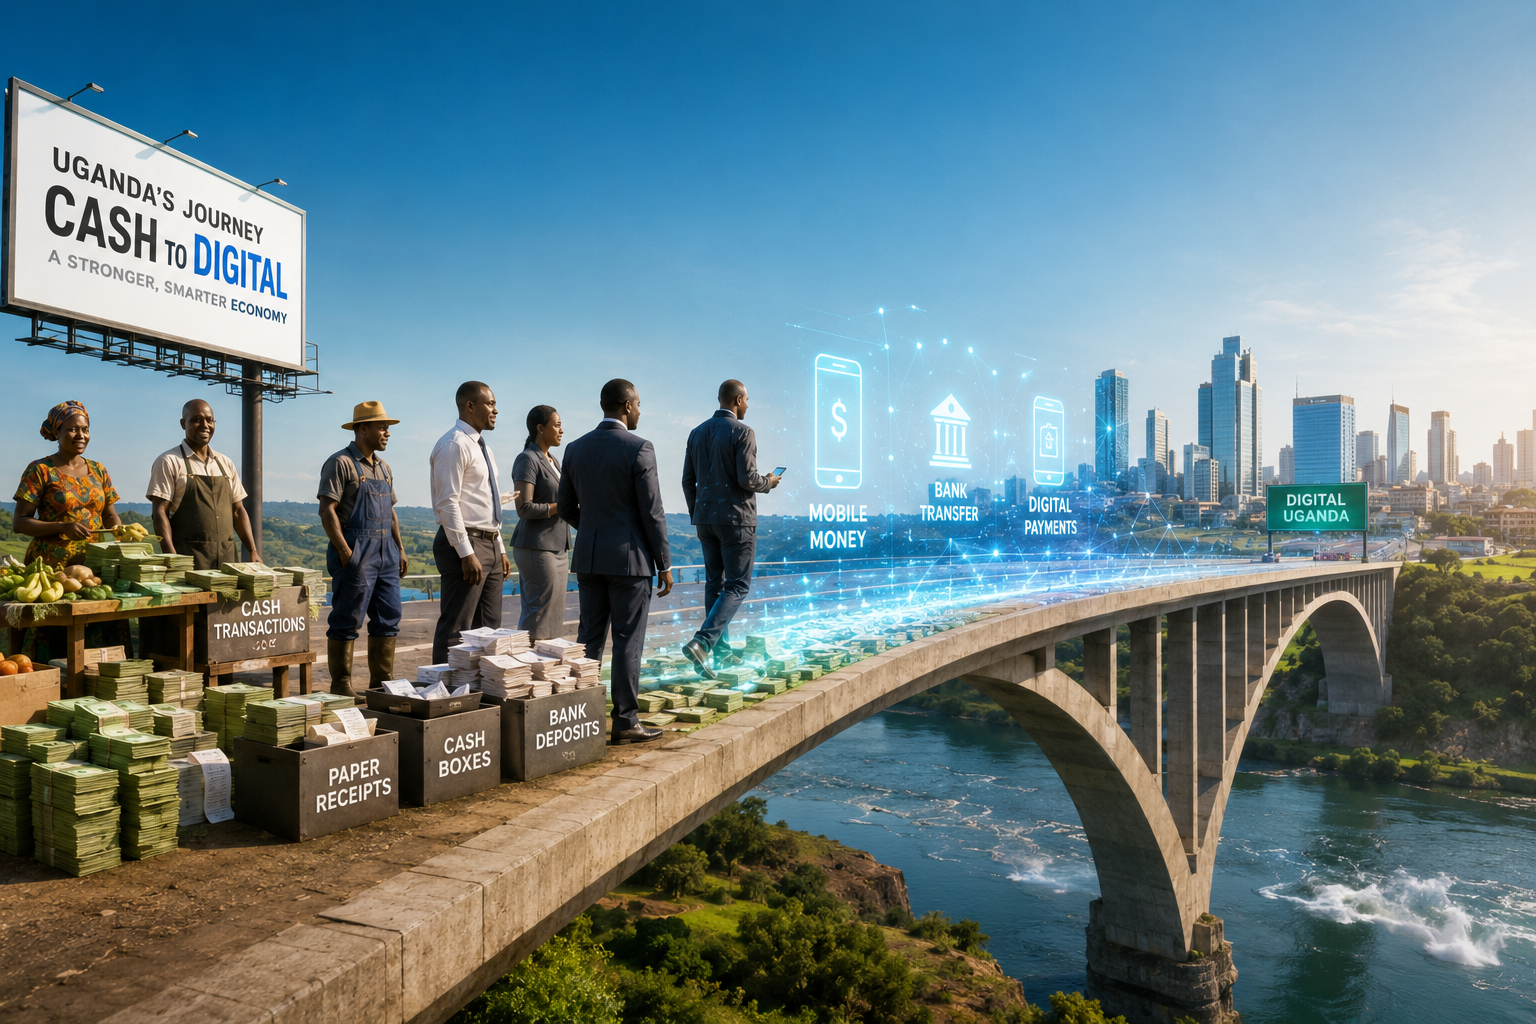
The Bank of Uganda (BOU) has announced significant changes to cash withdrawal limits that will take effect on January 1, 2027. Under the new policy, individual customers will be limited to withdrawing a maximum of UGX 50 million per day and UGX 500 million per week from their accounts at commercial banks. Corporate accounts will have higher limits, allowing withdrawals of up to UGX 250 million daily and UGX 2.5 billion weekly. These limits apply only to over-the-counter cash transactions and do not affect electronic transfers, such as RTGS, EFTs, mobile money, or other digital payment channels.
This move represents one of the most direct interventions by Uganda’s central bank to accelerate the shift from cash to digital financial services. For years, BOU has encouraged electronic payments through various initiatives, highlighting their benefits, including faster transaction speeds, greater transparency, reduced costs related to printing and handling physical currency, and improved security. The new limits build on the observed growth in digital adoption, as many Ugandans and businesses already prefer mobile money, internet banking, and card payments for both everyday and larger transactions.
The policy also allows for flexibility in exceptional cases. Financial institutions under supervision can request exemptions for clients in cash-intensive sectors such as agriculture, fuel distribution, or large-scale trading after conducting proper risk assessments and obtaining BOU approval. This provision acknowledges that not every economic activity can transition overnight to fully digital methods, particularly in rural areas or sectors dominated by cash due to infrastructure limitations or client preferences.
Uganda’s economy has experienced rapid digital transformation. Mobile money transactions have surged in both volume and value, while platforms like the Uganda National Interbank Settlement System continue to mature. BOU officials argue that an excessive reliance on cash imposes hidden costs on the financial system, including risks of theft, money laundering, and inefficiencies in supply chains. By capping large cash withdrawals, the central bank aims to encourage both individuals and businesses to adopt safer, traceable digital alternatives that also generate valuable data for credit scoring and economic planning.
For the average salary earner or small business owner, daily life may not change dramatically, as most transactions fall well below the new thresholds. However, the real impact will likely be felt by high-net-worth individuals, large corporations, and operators in sectors that frequently handle substantial cash volumes. These groups will need to plan ahead, diversify their payment methods, and perhaps strengthen their relationships with banks to secure necessary exemptions.
Banks themselves will also need to adapt. Customer service teams will require training on the new rules, while relationship managers will play a greater role in advising clients on digital alternatives. Over time, this shift could drive innovation in financial products tailored to a less cash-dependent economy.
The success of this policy will depend on effective execution and complementary measures. If digital infrastructure reliably expands into rural districts, transaction fees decrease, and public trust in electronic systems continues to grow, Uganda could emerge as a regional leader in cashless financial services. Ongoing challenges regarding cybersecurity, digital literacy, and last-mile connectivity will need attention.
As the January 1, 2027 deadline approaches, businesses and individuals would be wise to review their cash handling practices and explore digital tools that align with this new reality. The Bank of Uganda’s message is clear: the future of money in Uganda is increasingly digital, and the transition is not just encouraged but actively facilitated from the top.


Before You Write Off Uganda, Ask What You Have Contributed

Standard Chartered Uganda Retail Banking Migration to Absa Set for November 2026

A restriction on smallholder maize would trade food security for a cash-crop bet Uganda has already lost once


-
 Entertainment2 years ago
Museveni’s 2025 Copyright for Musicians breakdown
-

 Sports2 years ago
The Transformative Impact of World Cup Qualification for Uganda
-
 Business2 years ago
The 9 worst mistakes you can ever make at work
-
 Policies2 years ago
Breakdown of the Uganda Police Force Annual Crime Report 2024
-
 Business2 years ago
Uganda’s Ministry of Finance projects significant growth opportunities in 2025
-
 Policies2 years ago
Is Uganda’s Shs10m Fine the WORST Thing for Cohabiting Couples?
-
 Entertainment2 years ago
Uganda Cracksdown On Vulgar Music Content | Gloria Bugie, Shakira Shakira, targeted
-
 Health2 years ago
Breaking down the Malaria Vaccine Rollout in Uganda