Business
What Ugandans Need to Know About Green Financing
As of March 2025, they are drafting a policy to guide banks on financing projects.

As Uganda faces the impacts of climate change such as floods, droughts, and deforestation, green financing is emerging as a powerful tool for building a sustainable future. For everyday Ugandans, from farmers in Lamwo to business owners in Kampala, understanding green financing could mean access to new opportunities, improved livelihoods, and a healthier environment. Here’s what you need to know about this growing movement and how it is taking shape in Uganda.
Green financing refers to directing funds toward projects that protect the environment and combat climate change. This includes loans, investments, or funds for initiatives like solar power plants, energy-efficient buildings, and tree-planting projects. It is not just charity; it’s a way to make money work for both profit and the planet. In Uganda, this could involve financing cleaner cooking solutions or sustainable farming practices instead of activities like charcoal burning that harm forests.
The Bank of Uganda (BoU) is taking action. As of March 2025, they are drafting a policy to guide banks on financing projects. The main goal is to support eco-friendly ventures while making it more difficult for harmful ones to receive funding. For example, if you plan to borrow money to start a charcoal business, expect higher loan costs or stricter conditions. Why? Charcoal production contributes to deforestation and carbon emissions, exacerbating Uganda’s environmental crisis. Instead, the BoU aims for banks to back projects like renewable energy or agroforestry, consider solar panels for rural homes or coffee farms that also serve as carbon sinks.
This initiative is not entirely new. In 2024, the BoU collaborated with the Uganda Bankers Association to launch an ESG Framework which is short for Environmental, Social, and Governance. This framework serves as a roadmap for banks to prioritize sustainability, aligning with Uganda’s objectives for responsible growth. Green financing is a crucial aspect of this strategy.
For Ugandans, green financing is more than just policy, it has practical implications. If you are a farmer, it could provide access to cheaper loans for drip irrigation systems that conserve water. If you run a small business, energy-efficient upgrades could lower your utility bills and qualify you for better funding. Even households stand to benefit, imagine a green mortgage that rewards you for building a home with solar panels or good insulation.
Beyond individual benefits, the broader picture is crucial. Uganda is losing its forests rapidly being over 2% each year which contributes to climate instability. Green financing aims to reverse this trend, creating jobs in clean industries while improving air and water quality for everyone. Experts globally estimate that we need trillions of dollars to address climate change, and Uganda is part of that movement.
The BoU’s efforts may attract global investors. Countries like the UK are investing billions into green funds aimed at supporting Uganda, helping us build resilience against climate shocks. This presents an opportunity to leapfrog to cleaner technology, bypassing the dirty energy path that others have followed.
The transition to green financing will not be without challenges. Some concerns revolve around “greenwashing” where projects are marketed as environmentally friendly but fail to deliver real benefits. For instance, a solar company might promise significant savings but end up installing faulty panels, wasting money and eroding trust. Additionally, not every bank or business is prepared; some may resist change if it means short-term losses. For rural Ugandans, accessing these funds could be challenging if banks do not reach them or if the application process becomes overly complex.
There is also the issue of balance. Making charcoal loans more expensive could adversely impact small producers, especially those with limited alternatives. The BoU will need to pair this effort with support, such as training or funding for cleaner options, to avoid leaving vulnerable populations behind.
Green financing is part of a global shift known as ESG, which began decades ago when investors started avoiding harmful industries like tobacco. By the 2000s, it evolved into a system for assessing businesses based on their environmental impact, treatment of employees, and ethical leadership. Uganda is now catching up as climate pressures increase and global investments shift toward sustainability.
Keep an eye on the BoU’s policy, which is still in development as of March 2025. Inquire at your local bank about green loans or incentives for sustainable projects. If you are a community leader, advocate for awareness so rural areas are not overlooked. And if you are a student or entrepreneur, consider exploring green initiatives for there is a growing demand for innovators who can blend profit with purpose.
Green financing is not a magic solution, but it offers Uganda a chance to grow smarter. It is about investing in a future where the Rwenzori glaciers don’t vanish and where Lake Kyoga thrives.





Business
What Uganda’s Maize Story Tells Us About Future Opportunities
Maize is at the heart of Uganda’s farms, feeding families and generating livelihoods. With 69% of agricultural households growing it and 2.8 million metric tonnes produced, the numbers reveal a crop with enormous importance and opportunity.
If you ask any Ugandan farmer what they cultivate, there’s a high likelihood they’ll say maize. According to the Uganda Bureau of Statistics (UBOS), maize is the most widely grown crop in the country, cultivated by 69% of all agricultural households. It is more than just a crop; it represents a national habit, a source of livelihood, and a daily meal for millions of families.
In a recent agricultural season reported by UBOS, Ugandan farmers produced 2.8 million metric tonnes of maize. This output is not trivial; it reflects the hard work of hundreds of thousands of smallholder farmers across the country, from the central region to the west, who plant, tend to, and harvest this grain season after season.
The regions that excel in maize production tell an important story. Buganda North leads the country with 710,000 metric tonnes produced in that season, followed by Bunyoro with 561,000 metric tonnes and Buganda South with 266,000 metric tonnes. Together, these regions contribute well over a million tonnes of maize annually, highlighting the concentration of agricultural effort that has made maize the backbone of Uganda’s crop economy.
What happens to Uganda’s maize after it’s harvested is as significant as the quantity produced. UBOS data indicates that over 63% of the maize is sold in its raw, unprocessed form directly from farms to markets. Meanwhile, approximately 27.4% is retained by the households that grow it, providing food for their own families.
This distribution underscores maize’s dual role in Uganda: it serves both as a source of income and a safety net for food security. For many rural households, the same sack of maize sold at the local market this week might have fed the family just last month.
Maize’s rise has not occurred in a vacuum. Over the past decade, UBOS survey data shows a clear trend in Ugandan agriculture: households are shifting away from crops such as millet and beans and increasingly favoring maize, cassava, and bananas. Whether influenced by changing preferences, improved market access for maize, or consistent performance in various seasons, this trend toward maize has been steady.
We are closely studying this national picture. While we have not yet broken ground, we are in the early stages of deliberately planning the foundation for a farm that will be launched in the coming years. The data underscores why maize is central to our plan: it is the crop that Ugandan households already trust, grow, and rely on for both income and food security.
Starting a farm from scratch requires us to understand the market as it currently exists, not as we envision it. This means listening to what the data reveals about how Ugandan farmers grow, sell, and consume maize, which will inform the type of farm we aspire to create.
The seven out of ten farming households that already grow maize in Uganda are more than just a statistic; they are the community we are preparing to join.
Source: Uganda Bureau of Statistics (UBOS), 2019 Agricultural Survey; the most recent UBOS release with this level of crop-specific detail.
Business
Bank of Uganda Sets A Bold Push Toward Digital Payments With New Cash Withdrawal Limits.
The Bank of Uganda has introduced new over-the-counter cash withdrawal limits effective 1 January 2027, capping individuals at UGX 50 million daily and corporates at UGX 250 million. The policy aims to accelerate digital payments while sparking debate on its impact on cash-reliant sectors.
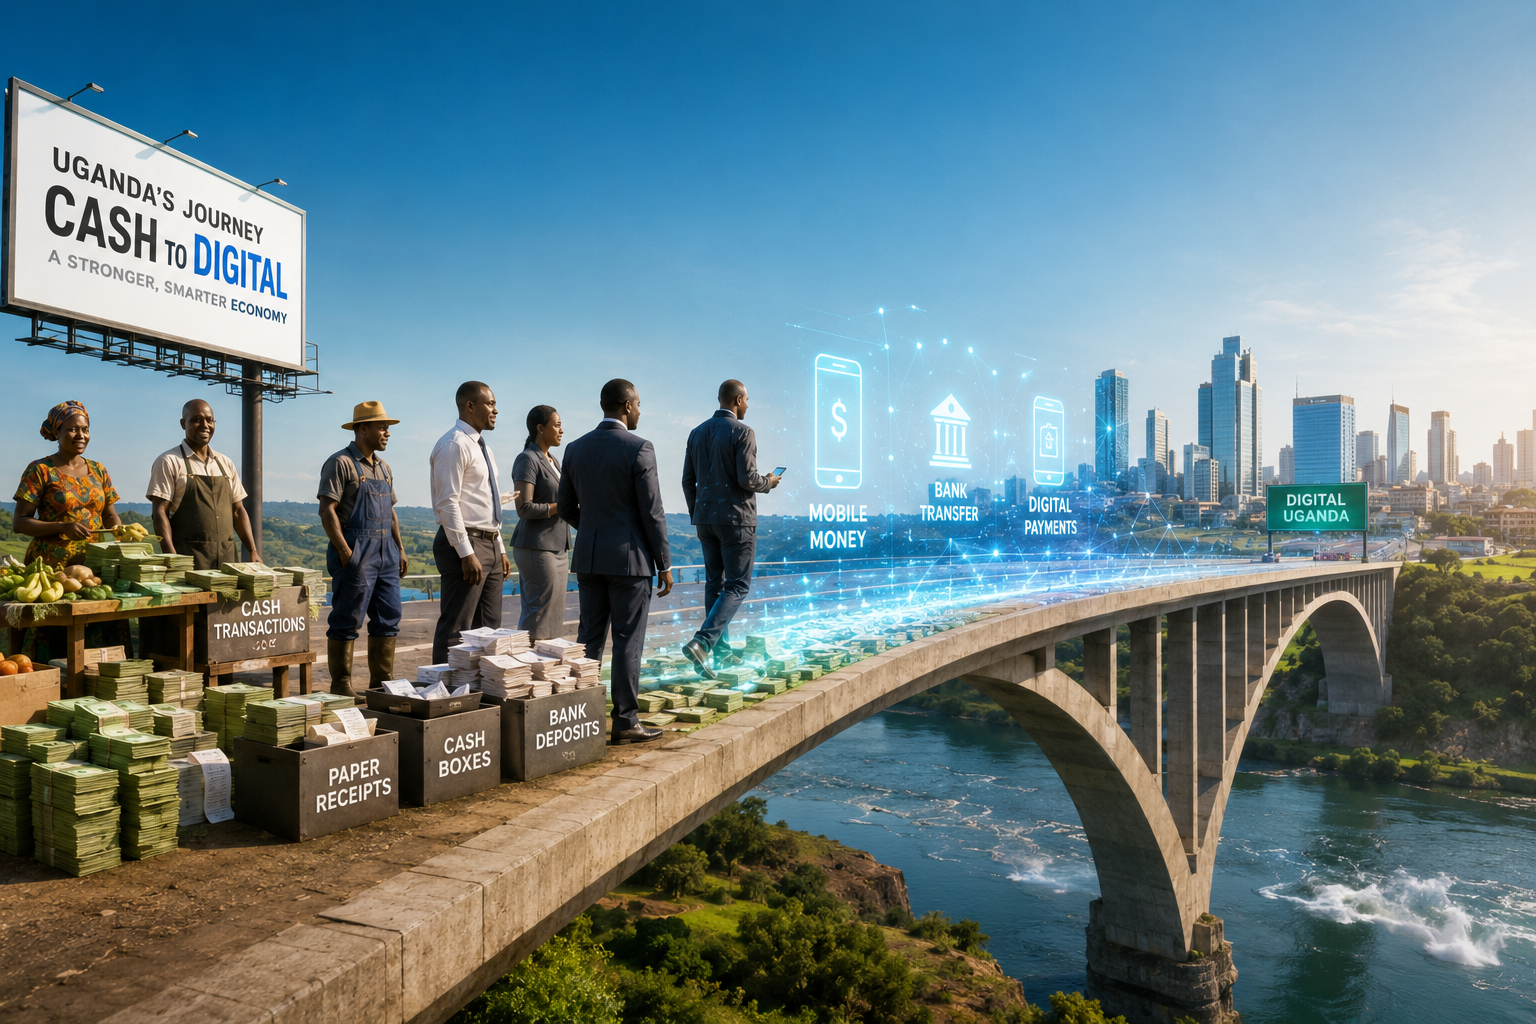
The Bank of Uganda (BOU) has announced significant changes to cash withdrawal limits that will take effect on January 1, 2027. Under the new policy, individual customers will be limited to withdrawing a maximum of UGX 50 million per day and UGX 500 million per week from their accounts at commercial banks. Corporate accounts will have higher limits, allowing withdrawals of up to UGX 250 million daily and UGX 2.5 billion weekly. These limits apply only to over-the-counter cash transactions and do not affect electronic transfers, such as RTGS, EFTs, mobile money, or other digital payment channels.
This move represents one of the most direct interventions by Uganda’s central bank to accelerate the shift from cash to digital financial services. For years, BOU has encouraged electronic payments through various initiatives, highlighting their benefits, including faster transaction speeds, greater transparency, reduced costs related to printing and handling physical currency, and improved security. The new limits build on the observed growth in digital adoption, as many Ugandans and businesses already prefer mobile money, internet banking, and card payments for both everyday and larger transactions.
The policy also allows for flexibility in exceptional cases. Financial institutions under supervision can request exemptions for clients in cash-intensive sectors such as agriculture, fuel distribution, or large-scale trading after conducting proper risk assessments and obtaining BOU approval. This provision acknowledges that not every economic activity can transition overnight to fully digital methods, particularly in rural areas or sectors dominated by cash due to infrastructure limitations or client preferences.
Uganda’s economy has experienced rapid digital transformation. Mobile money transactions have surged in both volume and value, while platforms like the Uganda National Interbank Settlement System continue to mature. BOU officials argue that an excessive reliance on cash imposes hidden costs on the financial system, including risks of theft, money laundering, and inefficiencies in supply chains. By capping large cash withdrawals, the central bank aims to encourage both individuals and businesses to adopt safer, traceable digital alternatives that also generate valuable data for credit scoring and economic planning.
For the average salary earner or small business owner, daily life may not change dramatically, as most transactions fall well below the new thresholds. However, the real impact will likely be felt by high-net-worth individuals, large corporations, and operators in sectors that frequently handle substantial cash volumes. These groups will need to plan ahead, diversify their payment methods, and perhaps strengthen their relationships with banks to secure necessary exemptions.
Banks themselves will also need to adapt. Customer service teams will require training on the new rules, while relationship managers will play a greater role in advising clients on digital alternatives. Over time, this shift could drive innovation in financial products tailored to a less cash-dependent economy.
The success of this policy will depend on effective execution and complementary measures. If digital infrastructure reliably expands into rural districts, transaction fees decrease, and public trust in electronic systems continues to grow, Uganda could emerge as a regional leader in cashless financial services. Ongoing challenges regarding cybersecurity, digital literacy, and last-mile connectivity will need attention.
As the January 1, 2027 deadline approaches, businesses and individuals would be wise to review their cash handling practices and explore digital tools that align with this new reality. The Bank of Uganda’s message is clear: the future of money in Uganda is increasingly digital, and the transition is not just encouraged but actively facilitated from the top.
Business
The Hidden Cost of Overloading Viewers: How Aggressive YouTube Ads Fuel Ad Fatigue and Damage Brands
A more serious concern arises when this accumulated frustration spills over. Viewers not only start disliking the ads but also develop genuine resentment toward the brands behind them.
Ad fatigue goes beyond mere annoyance; it reflects a psychological reaction that arises from how our brains process repeated interruptions and unwanted content. When viewers are exposed to excessive advertising, it generates irritation and a sense of lost control, known as psychological reactance, which leads to negative associations that transfer directly from the advertisement to the brand being promoted. As a regular YouTube viewer without a Premium subscription, I have personally witnessed this decline in user experience. Over the years, YouTube has gradually increased its ad volume through tactics like double pre-rolls, unskippable mid-roll placements, frequent irrelevant ads, and back-to-back interruptions. The availability of the platform’s own ad-free subscription subtly confirms that the current advertising strategy deteriorates overall user satisfaction.
A more serious concern arises when this accumulated frustration spills over. Viewers not only start disliking the ads but also develop genuine resentment toward the brands behind them. Ads that feel irrelevant or overly repetitive invade personal time and attention. When users provide feedback by marking an ad as irrelevant, only to continue seeing almost identical follow-up creatives from the same advertiser, it suggests that the feedback system is either malfunctioning or prioritized below revenue concerns. This cycle deepens resentment toward both the platform and the brand, turning neutral or passive viewers into actively hostile ones.
While advertisers and marketers cannot directly control YouTube’s platform policies, we can avoid contributing to this damage. Rushing high volumes of campaigns onto the platform in hopes of achieving conversions may yield short-term gains in impressions, but it poses a substantial long-term risk to brand health. An advertisement that harms brand sentiment is often more damaging than not running an ad at all. Such campaigns may accelerate the shift towards ad-free subscriptions, gradually undermining the effectiveness of paid reach over time.
A Better Approach; Earn Attention Rather Than Seize It, The most effective strategy is to prioritize contextual relevance over broad demographic targeting. Targeting based on age, location, or general interests often feels intrusive, while contextual relevance appears natural and genuinely helpful. For instance, when someone watches a cooking tutorial, an advertisement for kitchen tools or ingredients integrates seamlessly rather than feeling forced. Someone following a pottery tutorial connects better with promotions for clay, wheels, or kilns rather than an ad for a random food delivery service. The tighter the alignment between the advertisement and the viewer’s immediate interest, the less intrusive the experience becomes, minimizing the risk of negative emotional responses.
Respectful ad formats are also critical in reducing fatigue. Skippable advertisements, sponsored segments, and native integrations like creator mentions are generally perceived as less invasive than unskippable interruptions. If unskippable ads are necessary, they should be limited to six seconds or less, with the first one to three seconds designed to deliver an engaging hook that captures attention immediately. These practices demonstrate respect for the viewer’s time and sense of control.
Frequency management is one of the most powerful tools available. Overexposure is one of the quickest ways to turn indifference into hostility. Encountering the same ad five or more times in one session often triggers aversion. Advertisers should use platform tools to enforce strict impression caps such as three to five views per user per day or week; based on campaign objectives. Creatives should be rotated every two to six weeks, and frequency metrics should be diligently monitored to prevent fatigue
Every advertisement must justify the interruption it causes. The interaction should function as a true value exchange entertaining the viewer, providing useful information, solving a real problem, or delivering a clear incentive like a discount or practical tip. A thirty-second ad that wastes time breeds resentment, while one that feels helpful or enjoyable is more likely to be forgiven or even appreciated.
Shifting budget allocations away from purely interruptive formats towards channels that align with existing user intent is a crucial step. Using search advertisements on platforms like Google and YouTube, forming influencer partnerships, collaborating with creators, engaging in content marketing, and building community efforts tend to generate goodwill rather than resentment. This approach resonates with users because it aligns with their interests instead of forcing their attention.
Moreover, measurement should go beyond superficial metrics, such as Click-Through Rates, which don’t indicate whether engagement arises from genuine interest or irritation. More effective indicators include brand lift studies, analysis of comment sentiment, social listening data, and qualitative feedback. These tools provide better insights into potential negative associations. Declining View-Through Rates, increasing skip percentages, and the emergence of hostile comments are critical early warning signals that need immediate attention.
Bottom line, creating effective advertising is challenging, and meaningful conversions are often hard-earned. However, digital marketing achieves lasting success when attention is treated as something to be earned rather than taken. Campaigns that consistently respect context, timing, and user experience tend to foster genuine loyalty over the long term. Conversely, those that disregard these principles accelerate the shift toward ad-free subscriptions and undermine brand equity in ways that are difficult to reverse.
This perspective does not argue against advertising itself, but rather advocates for advertising that is sustainable and respectful of the audience it aims to reach. Have you observed brands that successfully reduced aggressive tactics after noticing clear signs of audience fatigue? I would be interested in hearing your experiences or examples.


What Uganda’s Maize Story Tells Us About Future Opportunities

Uganda Launches Evacuation of Nationals from South Africa Amid Rising Xenophobic Violence

Otto von Bismarck, The Marketing Genius Who Built an Empire and Hastened His Own Downfall


-
 Entertainment2 years ago
Museveni’s 2025 Copyright for Musicians breakdown
-

 Sports1 year ago
The Transformative Impact of World Cup Qualification for Uganda
-
 Business2 years ago
The 9 worst mistakes you can ever make at work
-
 Policies2 years ago
Breakdown of the Uganda Police Force Annual Crime Report 2024
-
 Business2 years ago
Uganda’s Ministry of Finance projects significant growth opportunities in 2025
-
 Entertainment2 years ago
Uganda Cracksdown On Vulgar Music Content | Gloria Bugie, Shakira Shakira, targeted
-
 Policies2 years ago
Is Uganda’s Shs10m Fine the WORST Thing for Cohabiting Couples?
-
 Health2 years ago
Breaking down the Malaria Vaccine Rollout in Uganda